Who pays for chiropractor after car accident in Georgia?
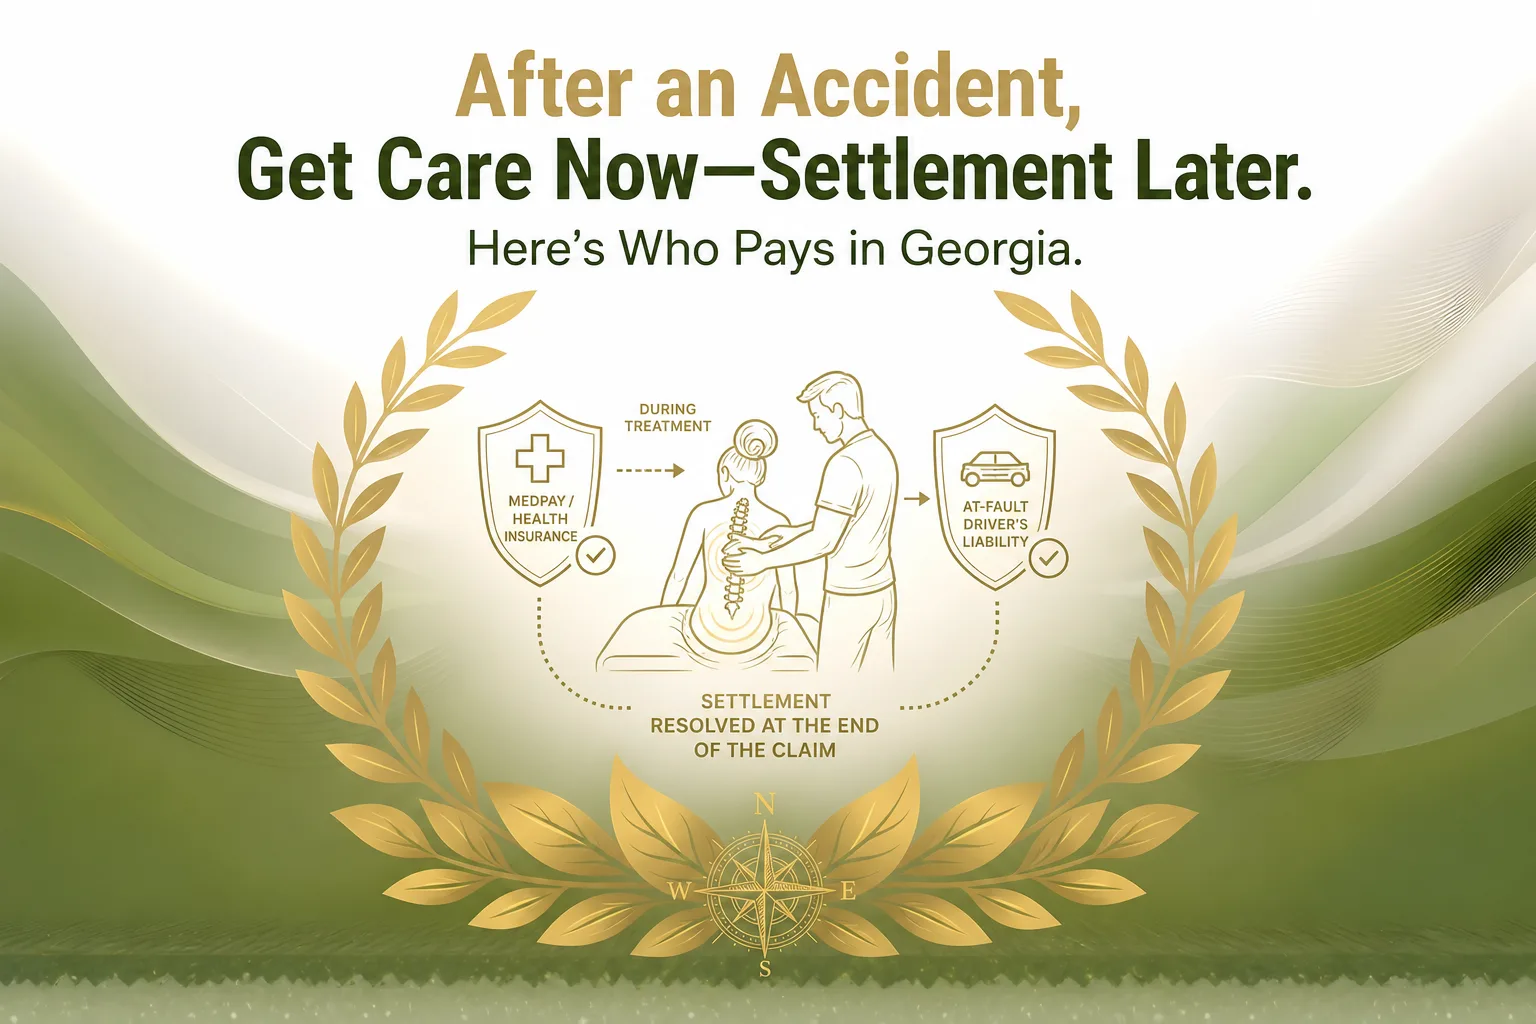
If you were just hit in Georgia, the short answer is that several different sources can pay for chiropractic care: MedPay on your own auto policy, your health insurance, uninsured or underinsured motorist coverage, or the at-fault driver’s liability insurance at the end of your claim. The part most people miss is the order. Some of those can start covering visits this week. Liability almost always pays at the very end.
The question we get on the first call: can I even afford to come in?
Most people who call our Woodstock office after a wreck are not calling on the day of the crash. They call on day two or day three, when the adrenaline has worn off and turning their head to back out of the driveway suddenly costs something. They describe the stiffness, the headache behind one eye, the night of bad sleep. And then, almost every time, the same sentence arrives: “I don’t know who’s paying for this yet, so I didn’t want to come in.”
That hesitation is the real problem. People do not delay care because they feel fine. They delay because they are afraid of walking into a bill they cannot plan for, or of doing something that quietly damages a claim they do not yet understand. Both fears are reasonable. Neither one is a good reason to spend three weeks sore and guessing.
The honest answer is that there is rarely one payer. There is a sequence. Something covers your care while you are healing, and something else may reimburse or resolve at the end. Once you can see that sequence, the money question usually gets a lot smaller.
What follows is what we see at the intake desk in Cherokee County every week — which paperwork patients actually arrive with, which pieces stall care, and what we can do while the rest is pending. It is not legal advice, and it is not a substitute for talking to an attorney or your own insurer about your specific policy. It is simply the practical view from the moment the question gets asked.
Who pays for chiropractor after car accident in Georgia: the five sources
Patients arrive with some combination of the following. You may have one. You may have three. Knowing which ones you hold changes everything about how quickly care can start.
1. MedPay on your own auto policy
Medical Payments coverage — almost always called MedPay — is optional first-party coverage you buy on your own auto policy. It pays reasonable medical expenses from a crash regardless of who caused it, usually up to a set limit such as $1,000, $5,000, or more. Chiropractic care is commonly a covered expense under MedPay, though the specific policy language controls.
MedPay is the single most useful thing to find out about on day one, because it can start paying while you are still treating. To check whether you have it, look at the declarations page of your auto policy — the summary page listing your coverages and limits — or call your agent and ask directly: “Do I carry Medical Payments coverage, and what is the limit?” A surprising number of people have it and do not know, because it was bundled in years ago and never used.
2. Your health insurance
Your regular health plan can usually be billed for crash-related care, subject to your normal deductible, copay, visit limits, and network rules. This is often the fastest path to consistent treatment when MedPay is small or absent. The trade-off is that health plans frequently have a right to be reimbursed later out of a settlement, which we cover further down.
3. Uninsured or underinsured motorist coverage (UM/UIM)
If the driver who hit you carried no insurance, fled, or carried limits too low to cover your damages, your own UM/UIM coverage may step in. Like liability coverage, it generally resolves as part of a claim rather than paying visit by visit, so it rarely funds care in real time. It matters enormously to your outcome, but it is not the thing that gets you adjusted this week.
4. The at-fault driver’s liability insurance — at settlement
This is the coverage everyone assumes will pay. It typically does pay, but once, at the end, as part of a negotiated resolution that covers medical bills, lost wages, and other damages together. That timing surprises people more than any other part of this process, so it gets its own section below.
5. Self-pay, payment arrangements, or an attorney letter of protection
If you have no MedPay and no health coverage, care does not have to stop there. Some patients pay out of pocket on a straightforward fee schedule. Others are represented by an attorney who issues a letter of protection — a written agreement that the provider will be paid from the eventual settlement rather than from the patient today. Whether a letter of protection is appropriate is a conversation between you and your attorney, not something we decide for you.
Why won’t the other driver’s insurance just pay my bills as I go?
Because Georgia is an at-fault state. There is no no-fault personal injury protection system here requiring each driver’s own insurer to pay medical bills immediately after a crash. Liability coverage exists to compensate someone who has been harmed by the insured driver — and from the insurer’s perspective, the full extent of that harm is not known until you have finished treating.
So the at-fault driver’s adjuster will take your report, open a claim, give you a claim number, and say some version of: “Send us your bills and records when you’re done and we’ll evaluate it.” That sentence sounds like a payment promise. It is not. It is an invitation to submit a package later. In the meantime, the clinic treating you still has to be paid by someone, and that someone is usually MedPay, your health plan, you, or a letter of protection.
This is the single biggest source of confusion on the first call, and it causes real harm. We regularly meet people who waited six weeks for the other driver’s insurance to “approve” chiropractic care that was never going to be approved visit by visit, because that is not how liability coverage works. They spent a month and a half stiff and sleeping badly for no reason, and the gap in their records created a second problem on top of the first.
A few practical notes from intake. A claim number being issued does not mean fault has been accepted. Property damage and bodily injury are often handled by different adjusters, so the person fixing your bumper may have no authority over your medical claim. And if an adjuster asks you for a recorded statement early on, it is entirely reasonable to say you would like to speak with an attorney first. None of that changes what your body needs, which is to be evaluated by someone who can document what is actually going on.
What changed in 2025: Georgia tort reform and why your treatment record carries more weight
If you have been searching this topic, you have probably run into recent commentary about Georgia’s 2025 tort reform legislation, Senate Bill 68. Georgia personal injury firms have been publishing explainers on it throughout the year — Hasner Law’s analysis of how the 2025 tort reform law affects injury claims in Atlanta and HC Injury Lawyers’ coverage of SB 68 and injury claims are two examples currently circulating. We are a chiropractic office, not a law firm, so we are not going to characterize the statute for you. What we can tell you is what the shift means at the level of a patient chart.
The consistent practical theme across the legal commentary is that injury claims in Georgia are being examined more closely than they were a few years ago — how injuries were documented, when care began, whether treatment was continuous, and how clearly the medical record connects the crash to the complaint. In other words, the parts of your claim that live in a clinical file rather than in an argument are carrying more weight.
That has three concrete consequences for you as a patient:
- When you started care matters. A long unexplained delay between the crash and the first evaluation invites the argument that something else caused your symptoms. If you were sore and simply did not know who would pay, that is understandable — and it is also exactly the kind of thing a clear record can address if care starts promptly.
- Gaps in treatment matter. Disappearing for five weeks mid-plan and returning later reads very differently from a steady, documented course of care with notes explaining any interruptions.
- Specificity matters. “Neck hurts, 6 out of 10” is a thin record. “Cannot check my blind spot without turning my shoulders, waking twice a night, headaches three days this week, can’t lift my toddler into the car seat” is a record that actually describes an injury’s effect on a life.
Please ask an attorney how the 2025 changes apply to your specific claim. Every crash is different, and the answer depends on facts we have no visibility into from the treatment side. Our role is narrower and simpler: evaluate you carefully, document honestly what we find, and keep the record clean enough that it tells the truth about your recovery on its own.
What to bring to your first visit — and what slows care down in our office
You do not need all of this to be seen. You need some of it for billing to move smoothly. Bring whatever you have:
- Your auto insurance declarations page, or your agent’s phone number, so we can confirm whether MedPay exists and what the limit is
- The claim number and the adjuster’s name and direct phone — for both your own carrier and the at-fault carrier if a claim has been opened
- The police report number or incident number, even if the full report is not available yet
- Your health insurance card
- Your attorney’s name and office contact, if you have retained one
- Any ER discharge paperwork, imaging, or urgent care notes from the days after the crash
- A short written list of what hurts, what you cannot do that you could do last week, and how you are sleeping
Here is what actually stalls things at our front desk. First, not knowing whether MedPay was purchased — this is the most common snag by far, and it is solved with one phone call to the agent whose number is on your insurance card. Second, a claim number that has not been assigned yet because the crash happened over a weekend or the carrier is still reaching the other driver. Third, waiting on a callback from an attorney’s office before scheduling anything at all.
None of those three need to stop your first visit. We can complete the examination, document findings on the date they exist, and begin care while coverage is confirmed in the background. Records can be forwarded to an adjuster or attorney after the fact without any difficulty.
On the related worry — will starting care before you talk to an attorney cause a problem? Getting evaluated promptly by a licensed provider and having your symptoms documented is ordinarily helpful, not harmful. Attorneys generally want to see that a client sought appropriate care. What creates problems is the opposite: a long silence in the record that no one can explain later.
Does using my own MedPay or health insurance hurt my settlement later?
This fear comes up on nearly every first call, and it deserves a straight answer rather than reassurance.
When your health plan or MedPay pays for crash-related treatment, that payer may have a right to be reimbursed out of any settlement you eventually receive. Depending on the plan, this is described as subrogation, a lien, or a reimbursement right. It does not usually mean you pay twice. It means that when the claim resolves, part of the proceeds may go back to the entity that fronted your care. Your attorney handles that accounting, and reimbursement amounts are frequently negotiated as part of the resolution.
What using your own coverage buys you is time — care that starts in days instead of months, during the window when early, consistent treatment is most useful for your recovery and most clearly documented in your record. That is a meaningful trade in both directions, which is exactly why the decision belongs to you and your attorney rather than to us. We will bill whichever source you direct us to bill.
Two related worries. “Will I use up my benefits?” MedPay limits are finite, and once exhausted, care typically shifts to health insurance, self-pay, or a letter of protection. Knowing your limit up front lets you plan rather than be surprised. “Will filing on my own policy raise my rates?” MedPay is a first-party benefit you already paid premiums for and used it as intended; questions about how any claim affects your specific premium should go to your agent, who can answer for your actual policy instead of in generalities.
Documentation habits that protect both your recovery and your claim
The same habits that make your record useful also make your care better, which is a happy coincidence rather than a strategy. A provider who knows precisely what you cannot do can build a smarter plan than one working from a pain number alone.
Describe function, not just intensity. Pain scales drift. Function does not. “I can’t sit through a full workday without standing up every twenty minutes” and “I stopped going to my Saturday class” tell us more than a 7 out of 10, and they age far better in a file.
Mention the things that feel unrelated. Headaches, jaw tightness, dizziness, ringing in the ears, trouble concentrating, and disrupted sleep are commonly reported after a collision. If you only report neck pain because that is the obvious one, the rest never enters the record.
Resist the reflex to say “I’m fine.” Most of us are polite by default. When someone asks how you are doing at visit four, answer the clinical question rather than the social one.
Keep appointments consistent. If life interferes — work travel, childcare, a flare-up of something else — tell us so the reason can be noted instead of leaving an unexplained blank.
Keep a simple log between visits. Three lines a day on your phone: what hurt, what you avoided, how you slept. It takes a minute and it makes your follow-up visits far more productive.
And the question people ask quietly: what if you stop treatment and the pain comes back? Tell us and tell your attorney. Returning for a documented re-evaluation is always better than pushing through silently, both for your recovery and for a record that otherwise shows a resolution that did not actually happen.
Coordinating chiropractic care with your physician, imaging, and an attorney
Co-managed care after a crash is normal. It is not a sign that something went wrong.
If your examination findings point toward something outside the scope of conservative care, we refer out — for imaging, for a medical evaluation, or to a specialist — and we keep treating alongside that provider where it is appropriate. Records are shared with your physician, your attorney, or an adjuster at your written request, and that process is routine.
Some symptoms belong in an emergency department rather than a chiropractic office, immediately: loss of consciousness, worsening or severe headache, confusion, repeated vomiting, numbness or weakness in an arm or leg, changes in vision or speech, severe abdominal pain, or any loss of bowel or bladder control. Please go be seen. Everything else can be sorted out afterward.
If you are in Woodstock, Towne Lake, Canton, Acworth, Kennesaw, Holly Springs, Marietta, or Roswell and you are sore after a wreck, you are welcome to call and ask the coverage questions before you commit to anything. We will help you figure out what you actually have, what it likely covers, and what a reasonable first step looks like — and if the answer is that you should call your agent or an attorney first, we will tell you that too.